-
₹4,550/-*
Starting professional fee (excl. Govt fees & taxes) -
3 Closure Routes
Voluntary, compulsory & strike-off -
Fast Track Exit
For dormant, inactive companies -
Form STK-2
Filed with the RoC for strike-off
Closing a Company in India
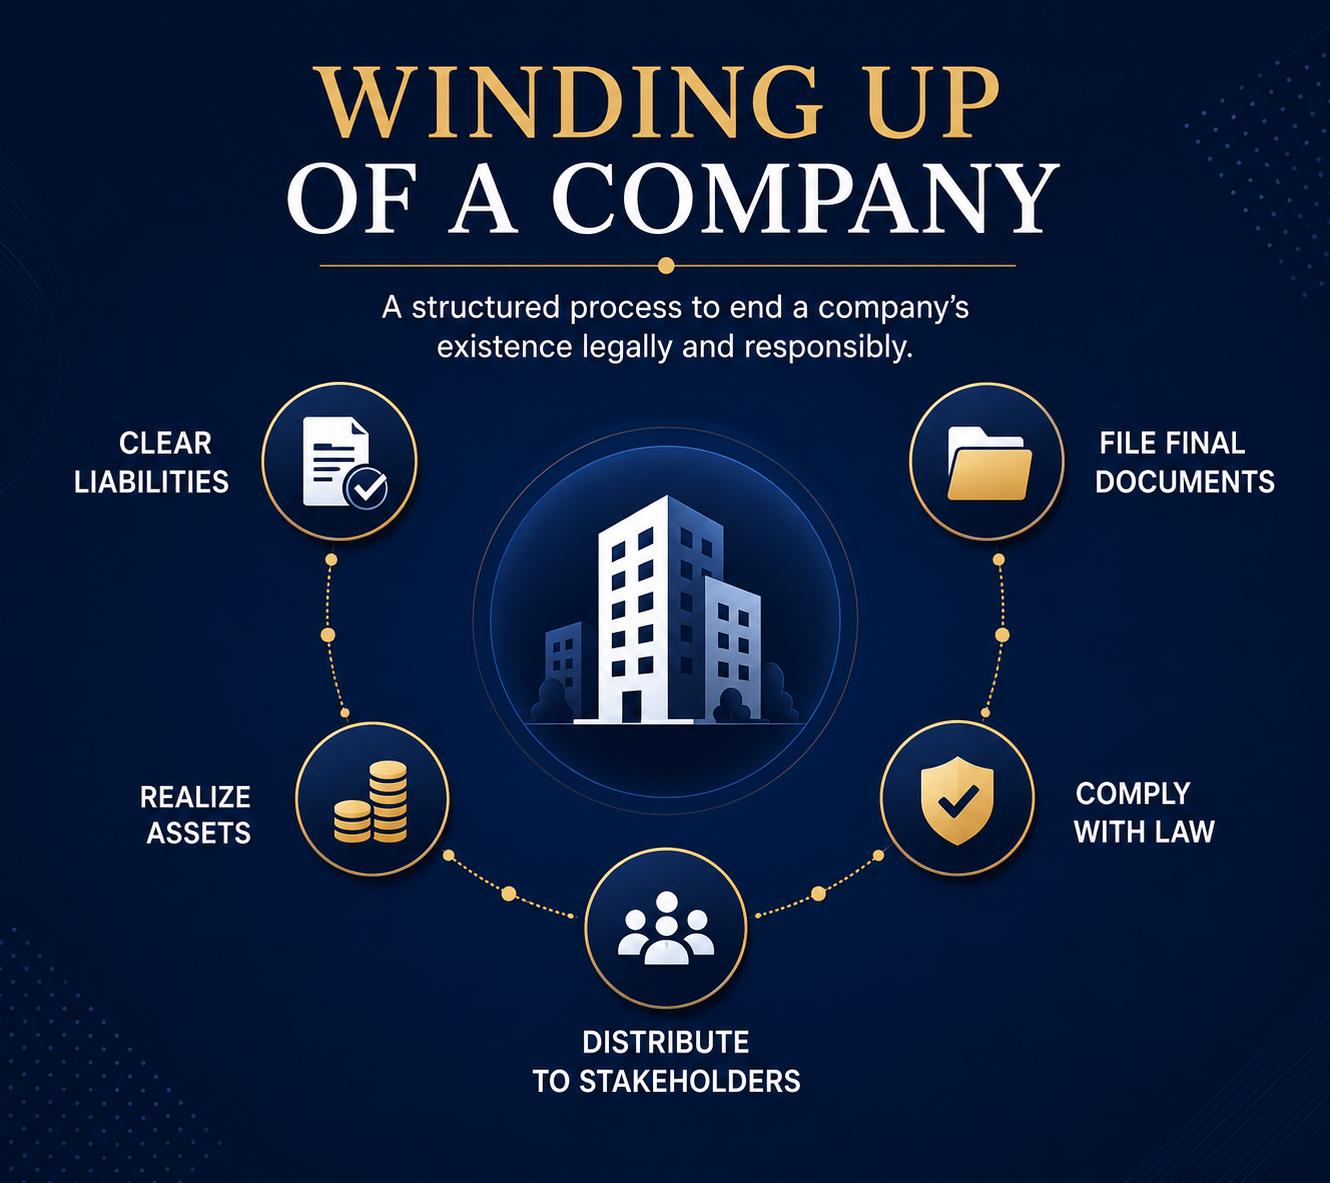
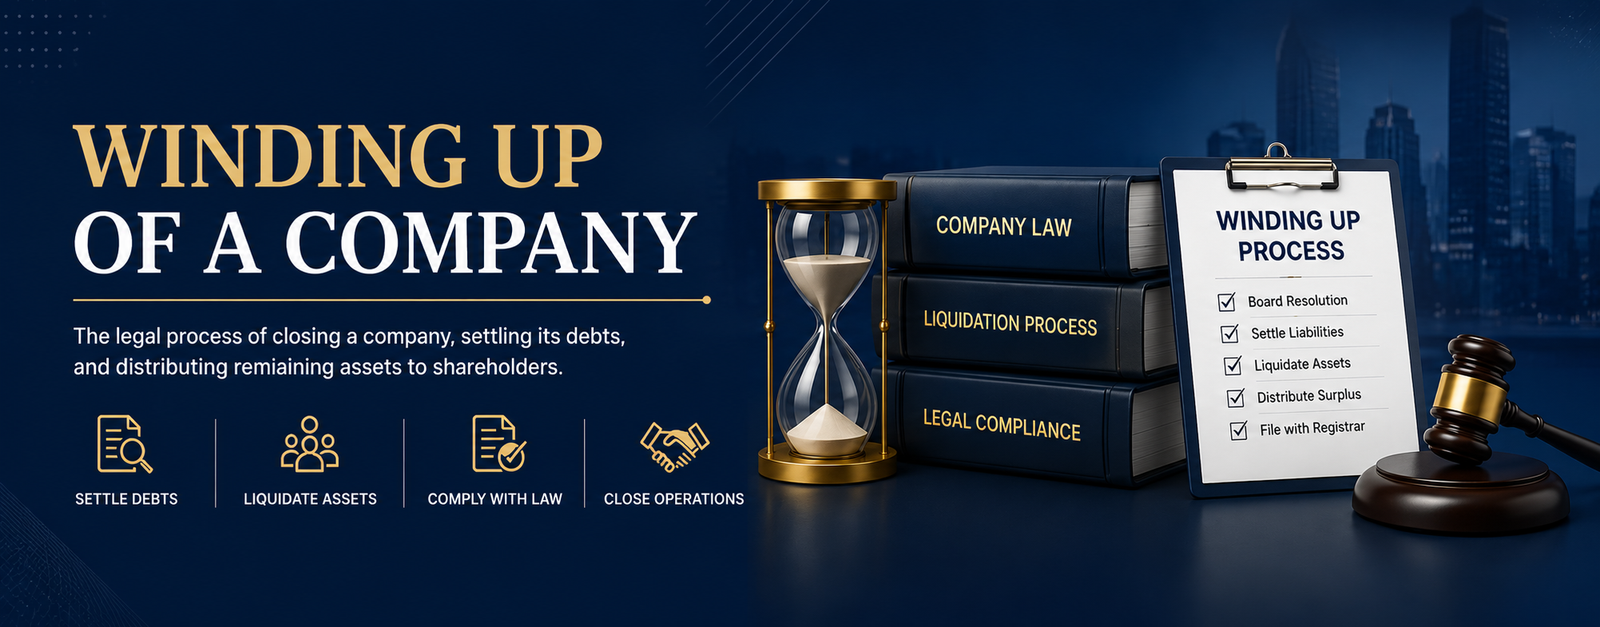
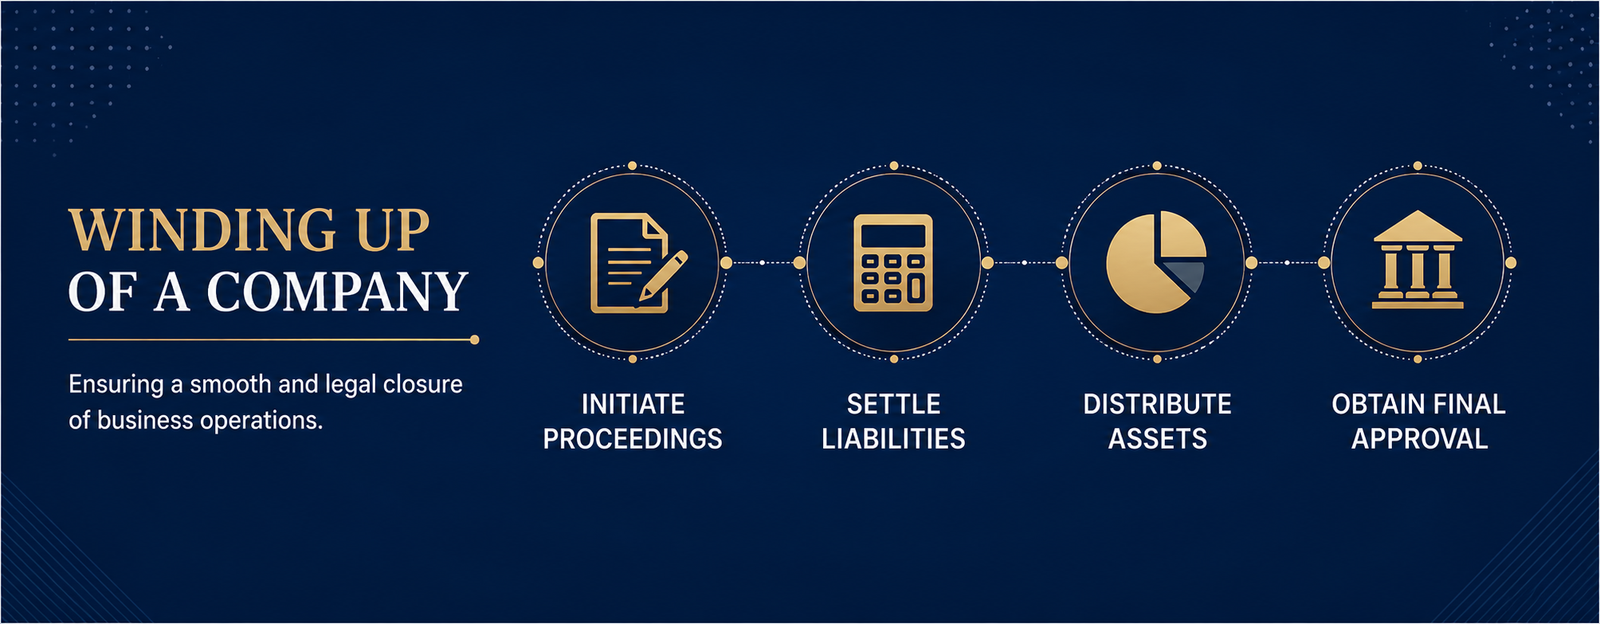
Winding up is the process of legally dissolving a company so it is no longer operational or required to meet statutory obligations. Closure can be voluntary — initiated by the company itself — or involuntary, ordered by the National Company Law Tribunal (NCLT). There are three routes available depending on the company's solvency, activity level, and circumstances.
-
Voluntary Winding Up Initiated by the shareholders and board when the company is solvent and wishes to cease operations.
-
Compulsory Winding Up Ordered by the NCLT due to insolvency, non-compliance, or fraudulent conduct.
-
Strike Off / Fast Track Exit A simplified route for dormant or inactive companies with no liabilities, via the Registrar of Companies.
Voluntary Closure (Members' Voluntary Winding Up)
A company closes voluntarily when its shareholders and management decide operations should cease — typically because the company has served its purpose, is no longer profitable, or for other business reasons.
-
Step 1: Board Resolution The board proposes closure, which must then be approved by at least 75% of shareholders at a general meeting.
-
Step 2: Declaration of Solvency If the company can pay off its debts, a declaration of solvency is filed with the Registrar of Companies (RoC) confirming liabilities can be cleared within a specified period.
-
Step 3: Appointment of Liquidator A liquidator is appointed to sell assets, settle liabilities, and distribute remaining assets to shareholders, taking charge of the company's affairs during the process.
-
Step 4: Creditors' Meeting Where creditors are involved, a meeting is held for their approval; creditors may also propose their own liquidator.
-
Step 5: Winding Up Application to NCLT An application is filed with the National Company Law Tribunal, submitting the board resolution, creditor consent, and other required documents.
-
Step 6: Completion & Dissolution The liquidator sells assets, settles debts and distributes remaining funds, then submits a final report. Once satisfied, the NCLT orders dissolution and the company's name is struck off the register.
Compulsory Closure (Involuntary Winding Up)
Compulsory winding up occurs when a company is forced to close for legal or regulatory reasons. The process is initiated by the court or NCLT.
-
Insolvency — unable to pay debts
-
Default in statutory filings for several years
-
Fraudulent or illegal conduct
-
Special resolution by shareholders to wind up via tribunal
-
Step 1: Filing of Petition Creditors, shareholders, or the Registrar of Companies may file a winding-up petition in the NCLT.
-
Step 2: NCLT Hearing The NCLT reviews the petition and, if satisfied, passes an order for winding up.
-
Step 3: Appointment of Official Liquidator An official liquidator is appointed and takes over the company's assets and operations.
-
Step 4: Liquidation of Assets The liquidator sells the company's assets, settles debts, and submits a final report to the NCLT.
-
Step 5: Dissolution Order The NCLT issues a dissolution order once liquidation is complete, and the company's name is struck off the register.
Strike Off by the Registrar of Companies (Fast Track Exit)
If a company has been inactive for two years or more, it can apply to have its name struck off the register through the Fast Track Exit (FTE) Scheme. The RoC can also strike off a company on its own initiative if it believes the company is not operational.
-
Step 1: Filing Form STK-2 Submitted to the RoC with a board resolution, indemnity bond, affidavit, and financial statements.
-
Step 2: Public Notice by RoC If the application is valid, the RoC publishes a public notice of the intended strike-off, allowing stakeholders time to raise objections.
-
Step 3: Name Struck Off If no objections are received, the RoC strikes the company's name off the register and it ceases to exist legally.
Key Documents & Consequences of Not Closing
-
Board and shareholders' resolutions
-
Declaration of solvency (if applicable)
-
Affidavit and indemnity bond
-
Audited financial statements
-
NOC from creditors
-
Application for striking off (Form STK-2)
-
Creditors' consent (voluntary liquidation)
-
Penalties & Fines Failure to file annual returns or financial statements can result in heavy penalties.
-
Director Disqualification Directors can be disqualified from holding future directorships for continued non-compliance.
-
Legal Consequences A company that remains legally active despite being inactive can face legal action and regulatory scrutiny.
FAQ for Company Closing in India
There are three primary ways to close a company in India:
- Voluntary Winding Up: Initiated by the company's shareholders.
- Compulsory Winding Up: Initiated by creditors, shareholders, or a tribunal due to insolvency, non-compliance, or other legal reasons.
- Strike Off by Registrar of Companies (RoC): For inactive or dormant companies, using the Fast Track Exit (FTE) Scheme.
A company qualifies for voluntary winding up if:
- The company is solvent and can pay its debts.
- The shareholders and board of directors agree to wind up the company.
- Creditors (if any) also approve the winding-up process.
To close a company using the FTE Scheme, the company must:
- File Form STK-2 with the RoC.
- Submit required documents such as board resolution, affidavit, indemnity bond, and financial statements.
- The RoC will publish a public notice.
- If no objections are raised, the RoC will strike off the company.
Key documents include:
- Board Resolution approving the closure.
- Shareholder Resolution (if applicable).
- Affidavit and Indemnity Bond.
- Declaration of Solvency (in case of voluntary winding up).
- Financial Statements.
- NOC from Creditors (if applicable).
- Filing Form STK-2 for strike-off.
Failure to properly close a company can result in:
- Penalties and Fines: For failure to file statutory documents and financial returns.
- Director Disqualification: Directors may be disqualified from holding future directorships.
- Legal and Financial Liabilities: The company and its directors could face legal action or financial obligations.
The cost of closing a company includes:
- Government filing fees for forms (e.g., Form STK-2 has a fee of ₹10,000 in India).
- Professional service fees for legal and administrative assistance.
- Additional costs if there are creditors or pending liabilities to settle.
FAQs
Get Personalized Quote for Winding Up
Fill in your details below and our compliance experts will guide you through the right closure route for your company — voluntary winding up, NCLT proceedings, or RoC strike-off.